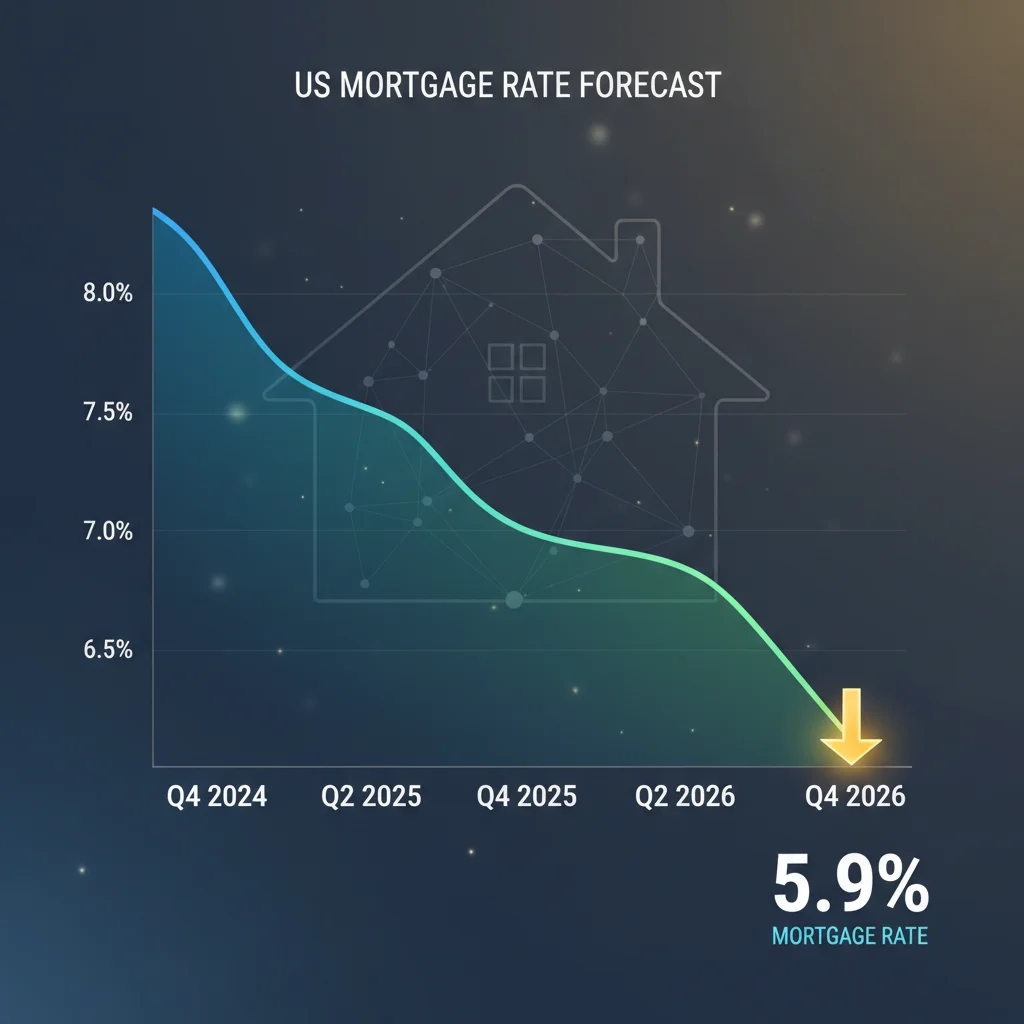
Mastering Mortgage Rates: Your Guide to Below 6.8% in Q4 2026
Anúncios
The housing market is a dynamic beast, constantly influenced by economic shifts, geopolitical events, and central bank policies. For prospective homebuyers and those looking to refinance, understanding and predicting mortgage rates is paramount. As we look towards Q4 2026, many are wondering: what will mortgage rates look like, and how can I secure a rate below 6.8%? This comprehensive guide delves into the intricate factors shaping future mortgage rates, offering strategic insights and actionable advice to help you navigate the landscape and achieve your homeownership dreams.
Anúncios
Understanding the Latest Mortgage Rate Trends: How to Secure a Rate Below 6.8% in Q4 2026
The journey to securing a favorable mortgage rate is often fraught with uncertainty. However, with careful planning, an understanding of economic indicators, and proactive strategies, achieving a rate below 6.8% in Q4 2026 is an attainable goal. This article will break down the forces at play, provide expert predictions, and equip you with the knowledge to make informed decisions.
Anúncios
The Macroeconomic Landscape: Influencing Mortgage Rates 2026
To predict mortgage rates, we must first understand the broader macroeconomic environment. Several key factors exert significant influence:
Inflation and Federal Reserve Policy
Inflation is arguably the most critical driver of interest rates. When inflation is high, the Federal Reserve typically raises the federal funds rate to cool down the economy. While the federal funds rate doesn’t directly dictate mortgage rates, it heavily influences the cost of borrowing for banks, which in turn impacts what they charge consumers. As we approach Q4 2026, the trajectory of inflation will be a primary determinant of the Fed’s stance. Current projections suggest a gradual easing of inflationary pressures, potentially allowing the Fed to adopt a more accommodative monetary policy, leading to lower mortgage rates. However, unforeseen economic shocks could alter this outlook.
The Fed’s actions are not just about controlling inflation; they also aim for maximum employment and stable long-term interest rates. Their forward guidance and meeting minutes provide invaluable clues about future policy directions. Keeping a close eye on these announcements is crucial for anyone monitoring mortgage rates 2026.
Economic Growth and Employment
A strong economy, characterized by robust GDP growth and low unemployment, often correlates with higher interest rates. This is because a thriving economy can absorb higher borrowing costs without significantly impacting consumer spending or business investment. Conversely, signs of an economic slowdown or recession can prompt the Fed to lower rates to stimulate activity. For Q4 2026, economists generally anticipate a period of moderate economic growth, a scenario that could support a gradual decline in mortgage rates from their recent peaks, but perhaps not a dramatic freefall.
Employment figures, particularly the monthly jobs report, are key indicators. A consistently strong job market might give the Fed less reason to cut rates aggressively, whereas a weakening labor market could accelerate rate reductions. The balance between growth and employment stability will be a delicate act for policymakers, directly impacting mortgage rates 2026.
Treasury Yields and Global Markets
Mortgage rates are closely tied to the yield on the 10-year Treasury note. This is because mortgage-backed securities (MBS), which are packaged loans sold to investors, compete with Treasury bonds for investment dollars. When Treasury yields rise, MBS yields must also rise to attract investors, leading to higher mortgage rates. Global economic conditions, geopolitical stability, and foreign investor demand for U.S. debt also play a role in influencing Treasury yields.
International events, such as conflicts, trade disputes, or economic downturns in major economies, can trigger a flight to safety, increasing demand for U.S. Treasury bonds and potentially pushing yields down. Conversely, global economic recovery and increased risk appetite could lead to higher yields. Therefore, understanding the global financial landscape is an essential component of forecasting mortgage rates 2026.
Expert Predictions for Mortgage Rates 2026
While no one has a crystal ball, financial institutions and economic analysts offer projections based on sophisticated models and current data. Many anticipate that by Q4 2026, mortgage rates will likely settle into a more moderate range compared to the elevated levels seen in recent years. The consensus often points towards rates hovering around the mid-6s, making the target of below 6.8% a realistic, albeit competitive, aspiration.
Factors Supporting Lower Rates
- Easing Inflation: A continued trend of decreasing inflation will provide the Federal Reserve with more flexibility to lower the federal funds rate, which should translate to lower long-term mortgage rates.
- Stabilized Economic Growth: A period of stable, but not overheating, economic growth could allow interest rates to normalize without significant upward pressure.
- Increased Housing Supply: While a long-term challenge, any significant increase in housing inventory could temper demand and contribute to a more balanced market, potentially easing upward pressure on rates.
Potential Headwinds
- Persistent Inflation: If inflation proves more stubborn than anticipated, the Fed might be forced to maintain higher rates for longer, pushing mortgage rates higher than expected.
- Geopolitical Instability: Unforeseen global conflicts or economic crises could create market volatility, driving up rates as investors seek safe havens or demand higher returns for risk.
- Strong Economic Resurgence: A surprisingly robust economic rebound could lead to renewed inflationary pressures and a more hawkish Fed stance.
It’s crucial to remember that these are predictions, and the market is subject to rapid changes. Staying informed through reputable financial news sources and consulting with mortgage professionals is always recommended.
Strategies to Secure a Mortgage Rate Below 6.8% in Q4 2026
Even with favorable market conditions, securing the best possible mortgage rate requires proactive planning and strategic execution. Here are several key strategies:
1. Improve Your Credit Score
Your credit score is one of the most significant factors lenders consider when determining your interest rate. A higher credit score (typically FICO scores above 740-760) signals to lenders that you are a low-risk borrower, qualifying you for better terms and lower rates. Start working on improving your credit score well in advance of your home purchase or refinance.
- Pay Bills on Time: Payment history accounts for 35% of your FICO score.
- Reduce Debt: Lower your credit utilization ratio (the amount of credit you’re using compared to your total available credit). Aim for below 30%, ideally below 10%.
- Avoid New Credit: Don’t open new credit accounts or make large purchases on credit before applying for a mortgage, as this can temporarily lower your score.
- Check for Errors: Regularly review your credit report for inaccuracies and dispute any errors immediately.
2. Save for a Larger Down Payment
A larger down payment reduces the amount you need to borrow, which can translate into a lower interest rate. Lenders view borrowers with substantial equity from the outset as less risky. While 20% is often considered ideal to avoid private mortgage insurance (PMI), even putting down more than the minimum required can positively impact your rate.
- Reduced Loan-to-Value (LTV): A lower LTV ratio often results in a more attractive rate.
- Lower Monthly Payments: A larger down payment means a smaller loan amount, leading to lower monthly payments.
- Increased Lender Confidence: Demonstrates financial stability and commitment.
3. Shop Around for Lenders
This cannot be stressed enough. Mortgage rates can vary significantly between lenders, sometimes by as much as half a percentage point or more for the same borrower. Don’t settle for the first offer you receive. Contact multiple lenders—banks, credit unions, and mortgage brokers—to compare rates, fees, and terms.
- Get Multiple Quotes: Apply with at least three to five different lenders.
- Compare APR vs. Interest Rate: Look at the Annual Percentage Rate (APR), which includes fees, to get a true comparison of the total cost of the loan.
- Negotiate: Use competing offers to negotiate for a better rate or lower fees.
4. Consider a Mortgage Rate Lock
Once you’ve found a favorable rate, consider locking it in. A rate lock guarantees your interest rate for a specific period (typically 30, 45, or 60 days) while your loan processes. This protects you if rates rise before closing. Be aware of the lock-in period and any associated fees, especially if you anticipate a lengthy closing process.
- Protection Against Rate Hikes: Ensures your agreed-upon rate won’t increase.
- Understand Lock Terms: Know the duration of the lock and what happens if it expires.
- Float-Down Option: Some lenders offer a ‘float-down’ option, allowing you to get a lower rate if market rates drop significantly before closing (often for an additional fee).
5. Explore Different Loan Types
While fixed-rate mortgages are popular for their stability, other loan types might offer lower initial rates. Adjustable-rate mortgages (ARMs) typically start with a lower interest rate for an initial period (e.g., 5, 7, or 10 years) before adjusting. If you plan to sell or refinance before the adjustment period, an ARM could be a viable option to secure a lower initial rate.
- Fixed-Rate Mortgage: Predictable payments, but initial rates might be higher.
- Adjustable-Rate Mortgage (ARM): Lower initial rates, but payments can fluctuate after the fixed period. Evaluate your risk tolerance and future plans carefully.
- Government-Backed Loans: FHA, VA, and USDA loans often have more flexible qualification requirements and competitive rates, though they come with specific eligibility criteria.
6. Pay for Discount Points
Discount points are prepaid interest that you pay at closing to reduce your interest rate over the life of the loan. One point typically costs 1% of the loan amount and can lower your interest rate by 0.125% to 0.25%. Calculate whether paying points makes financial sense for your situation, considering how long you plan to stay in the home.
- Lower Interest Over Time: Can lead to significant savings on interest payments if you stay in the home long enough.
- Upfront Cost: Requires more cash at closing.
- Break-Even Point: Calculate how long it takes for the savings from the lower interest rate to offset the cost of the points.
7. Monitor Economic News and Fed Announcements
Stay informed about economic data releases, inflation reports, and Federal Reserve meetings. These events can trigger immediate shifts in mortgage rates. Being aware of these trends allows you to time your mortgage application or rate lock strategically. Financial news outlets, reputable economic blogs, and the Federal Reserve’s official communications are excellent resources.
- Inflation Data: Consumer Price Index (CPI) and Producer Price Index (PPI) are key indicators.
- Employment Reports: Non-farm payrolls and unemployment rates.
- FOMC Meetings: Federal Open Market Committee announcements on interest rate policy.
The Role of Technology in Securing Favorable Mortgage Rates 2026
Technological advancements have revolutionized the mortgage application process, making it easier than ever to compare rates, apply for loans, and manage your finances. Leveraging these tools can significantly aid your quest for a mortgage rate below 6.8% in Q4 2026.
Online Mortgage Calculators and Comparison Tools
Numerous online platforms allow you to compare mortgage rates from various lenders simultaneously. These tools often provide personalized rate estimates based on your credit score, location, and down payment amount. They also offer calculators to estimate monthly payments, total interest paid, and the impact of discount points.
- Instant Rate Quotes: Get an idea of current rates without formal applications.
- Scenario Planning: Experiment with different down payment amounts, loan terms, and credit scores to see their impact on rates.
- Transparency: Helps demystify the complex world of mortgage rates and fees.
AI and Predictive Analytics
Some financial technology (FinTech) companies are utilizing AI and machine learning to predict future rate movements with greater accuracy. While these tools are still evolving, they can offer valuable insights into potential trends, helping you decide when to lock in a rate or when to wait. Consulting with a mortgage advisor who leverages such technologies can provide an edge.
- Data-Driven Forecasts: Leverage vast datasets to identify patterns and predict future rate changes.
- Personalized Advice: AI can analyze your financial profile and offer tailored recommendations.
Digital Mortgage Applications and Closings
The move towards digital mortgage applications has streamlined the entire process. Online portals allow for secure document submission, real-time status updates, and even digital closings in some regions. This efficiency can be critical when trying to lock in a rate quickly before market shifts.
- Speed and Efficiency: Faster application and approval processes.
- Convenience: Complete paperwork from anywhere, at any time.
- Reduced Errors: Digital platforms often have built-in checks to minimize mistakes.
Refinancing Opportunities in Q4 2026
For current homeowners, Q4 2026 could present a significant refinancing opportunity if mortgage rates indeed fall below 6.8%. Refinancing allows you to secure a lower interest rate, reduce your monthly payments, or even tap into your home equity. The same strategies for securing a new mortgage apply to refinancing.
- Interest Rate Reduction: Lower your monthly payments and save thousands over the life of the loan.
- Term Reduction: Shorten your loan term (e.g., from 30 to 15 years) to pay off your mortgage faster.
- Cash-Out Refinance: Access your home equity for home improvements, debt consolidation, or other financial needs.
- Adjustable to Fixed-Rate: Convert an ARM to a fixed-rate mortgage for payment stability.
Before refinancing, carefully weigh the closing costs against the potential savings. A good rule of thumb is to calculate your break-even point – how long it will take for your monthly savings to cover the refinancing costs. If you plan to stay in your home beyond that point, refinancing is likely a sound financial decision.
The Importance of a Qualified Mortgage Professional
Navigating the complexities of mortgage rates and loan options can be overwhelming. A qualified mortgage professional – whether a loan officer at a bank or an independent mortgage broker – can be an invaluable resource. They can:
- Provide Personalized Advice: Assess your financial situation and recommend the best loan products for your needs.
- Access Multiple Lenders: Mortgage brokers, in particular, work with a network of lenders, potentially finding you better rates than you could on your own.
- Explain Complex Terms: Help you understand the fine print, fees, and implications of different loan structures.
- Guide You Through the Process: From application to closing, they can ensure a smooth and efficient experience.
Look for professionals with strong reviews, extensive experience, and a deep understanding of current market conditions and future forecasts for mortgage rates 2026.
Conclusion: Positioning Yourself for Success in Q4 2026
The prospect of securing a mortgage rate below 6.8% in Q4 2026 is a tangible goal for prepared homebuyers and homeowners. While the market remains unpredictable, understanding the macroeconomic drivers, staying informed about expert predictions, and implementing smart financial strategies will significantly increase your chances of success. Focus on improving your credit, saving for a substantial down payment, diligently shopping for lenders, and leveraging available technology.
Remember, the housing market rewards those who are patient, informed, and proactive. By taking these steps, you can confidently approach Q4 2026, ready to capitalize on potentially favorable mortgage rates and make your homeownership dreams a reality. Keep a close watch on the economic indicators, consult with trusted professionals, and be prepared to act when the timing is right to lock in that desirable mortgage rate 2026.
This comprehensive approach will not only help you secure a great rate but also ensure that your home financing is sound and sustainable for years to come. The future of mortgage rates 2026 looks promising for those who are well-prepared.